Kelsey Easton October 19, 2026
On a $1.5M Austin purchase with 20% down, most buyers should plan on roughly $30,000 to $36,000 in closing costs, or about 2% to 2.5% of the price, and about $37,000 to $44,000 if the buyer ends up paying for the owner's title policy. A cash buyer will land far lower, since lender fees, prepaid interest, and the lender's title policy disappear. The exact number swings mostly on three things: how many discount points you buy, what your insurance and property tax prepaids look like, and who pays for the title policy.
I walk clients through this number before we ever write an offer, because at this price point a surprise of $10,000 is not unusual. Here is how it breaks down.
These are illustrative numbers for a $1.5M home, $300,000 down, and a $1.2M loan. They are my budgeting estimates, not a quote, and your lender and title company will give you the real figures.
Add those up, and you land between about $30,000 and $36,000 depending on whether you buy half a point or a full point. Home inspections, the appraisal, and your option fee are paid before closing, so budget for those separately.
Under the standard Texas contract used in the Austin market, the seller customarily pays for the owner's title policy, but it is negotiable. Texas sets title insurance premiums, so the price doesn't change from one title company to the next. Under the rate card effective March 1, 2026, published by Republic Title, the owner's policy on a $1,500,000 purchase is $7,256. If a seller asks you to take that on in a competitive negotiation, that is real money, and you should weigh it like any other concession.
What you can shop is the settlement fee, the survey, and the escrow service.
Discount points. Every point on a $1.2M loan is $12,000. Whether it makes sense depends on how long you plan to stay and what a lower rate saves you each month. I would rather you run that break-even calculation with your lender than guess.
Prepaids. People call these closing costs, but they are really your own money going into escrow. At this level, the insurance premium and tax escrow are often the largest line items after points. If you are buying in West Lake Hills or another Eanes ISD area, the tax rate and your premium will look different than in a MUD or PID community, which can add its own assessment on top. I cover that in my guide on the true cost of owning a $2M home in Austin.
Your price and your lender. Costs that are a percentage of the loan scale with the price. A Tarrytown buyer at $1.5M and a buyer at $2.5M will see title premiums, points, and prepaids all climb with the price, so budget from your own price rather than a rule of thumb.
Sellers have their own list. Their largest items are typically the owner's title policy, agent compensations, any repair or closing cost credits negotiated after the option period, and the payoff of the existing mortgage. Texas has no state transfer tax, which helps both sides. Property taxes are prorated at closing, so the seller reimburses the buyer for the days they owned the home.
Plan on 2% to 2.5% of the purchase price for a financed $1.5M home, which is $30,000 to $36,000, and add $7,256 if the owner's title policy ends up on your side. Treat the estimate as a range until your lender issues a Loan Estimate, and ask for it before you make an offer, not after. If you want a line-by-line number built around your down payment and the specific homes you are considering, send me a note and I will put it together.
Yes. A cash buyer skips origination, lender fees, the lender's title policy, and prepaid interest. You still pay the settlement fee, survey, and any owner's policy you negotiate, plus the property tax proration at closing.
On a purchase, you generally cannot finance them on top of the loan. The usual tools are seller concessions, a lender credit in exchange for a slightly higher rate, or paying them out of pocket.
Yes, but not proportionally. The state rate schedule climbs on a sliding scale, so the owner's policy at $1.5M is $7,256 under the rates effective March 1, 2026. Your title company can quote the exact figure for your price.
Your lender must give you a Loan Estimate within three business days of your application, and a Closing Disclosure at least three business days before closing. Review both against my estimate and ask questions on anything that looks off.
If you're thinking about buying or selling in Austin at the $1M+ level, I'd love to chat.
Kelsey Easton, Compass Austin
(512) 699-6091
[email protected]
Connect with me on Zillow
Buying, selling, or just exploring? Let's connect.
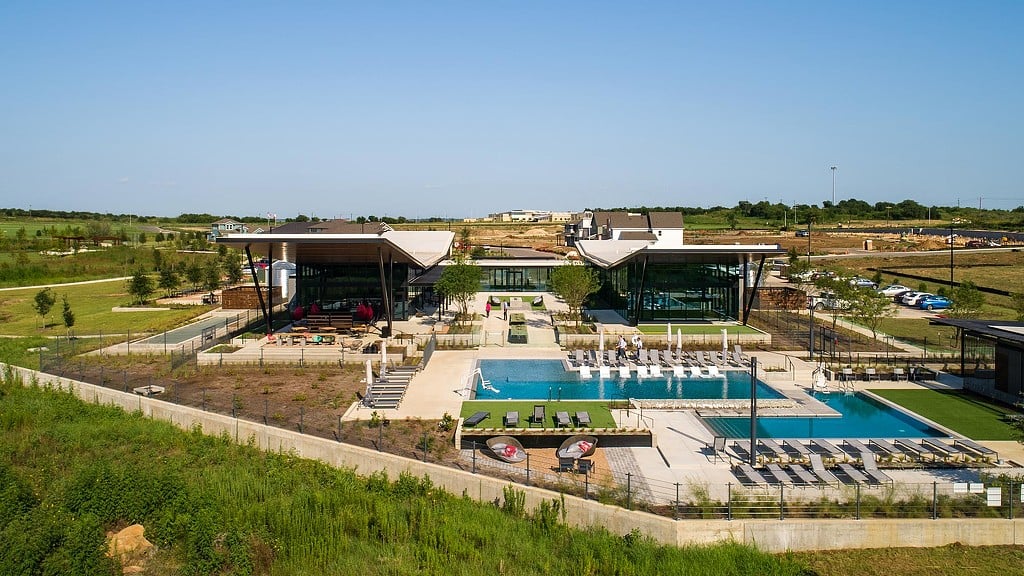
What I'm seeing from five recent Easton Park deals: builder incentives, resale pricing, and where the market goes into year end.
Dallas gets you more house; Austin gets you the Hill Country, the lake, and a market where patient $1M+ buyers have leverage. Here's how to choose.
Early access is not the same as a discount. Here is how I help $1M+ buyers decide whether a private Austin listing is worth pursuing.
Buying
Real listings, real photos and real numbers from Downtown to Dripping Springs: the best-looking finished homes around $1 million in each part of Austin right now.
I will not guess at a number, but the latest $1M+ data shows a steady market with more inventory and real room to negotiate. Here is what it means for buyers and selle… Read more
September and October 2026 MLS data: where Austin luxury buyers have leverage by price tier and neighborhood, and how much is selling off market.
A line-by-line look at what a financed $1.5M Austin purchase really costs at the closing table, and who typically pays for what.
Most $1M+ Austin closings take 30 to 45 days, and cash deals can close in two weeks. Here's what controls the clock and how to keep your deal on schedule.

Rates are near 7% and sellers are cutting prices. Here is what the latest numbers mean for your leverage.
Get in Touch
KELSEY EASTON
2500 BEE CAVES RD WEST LAKE HILLS TX 78746